Personal finance
Banco de la República rates at 12.25%: what changes for the investor
After a cycle of cuts, the Banco de la República raised rates again in 2026. We explain why and its effects on real estate investment.
October 23, 2026 4 min readCityFraction editorial team
Key points
- The Banco de la República lowered the rate to 9.25% in April 2025 and kept it there for the rest of that year.
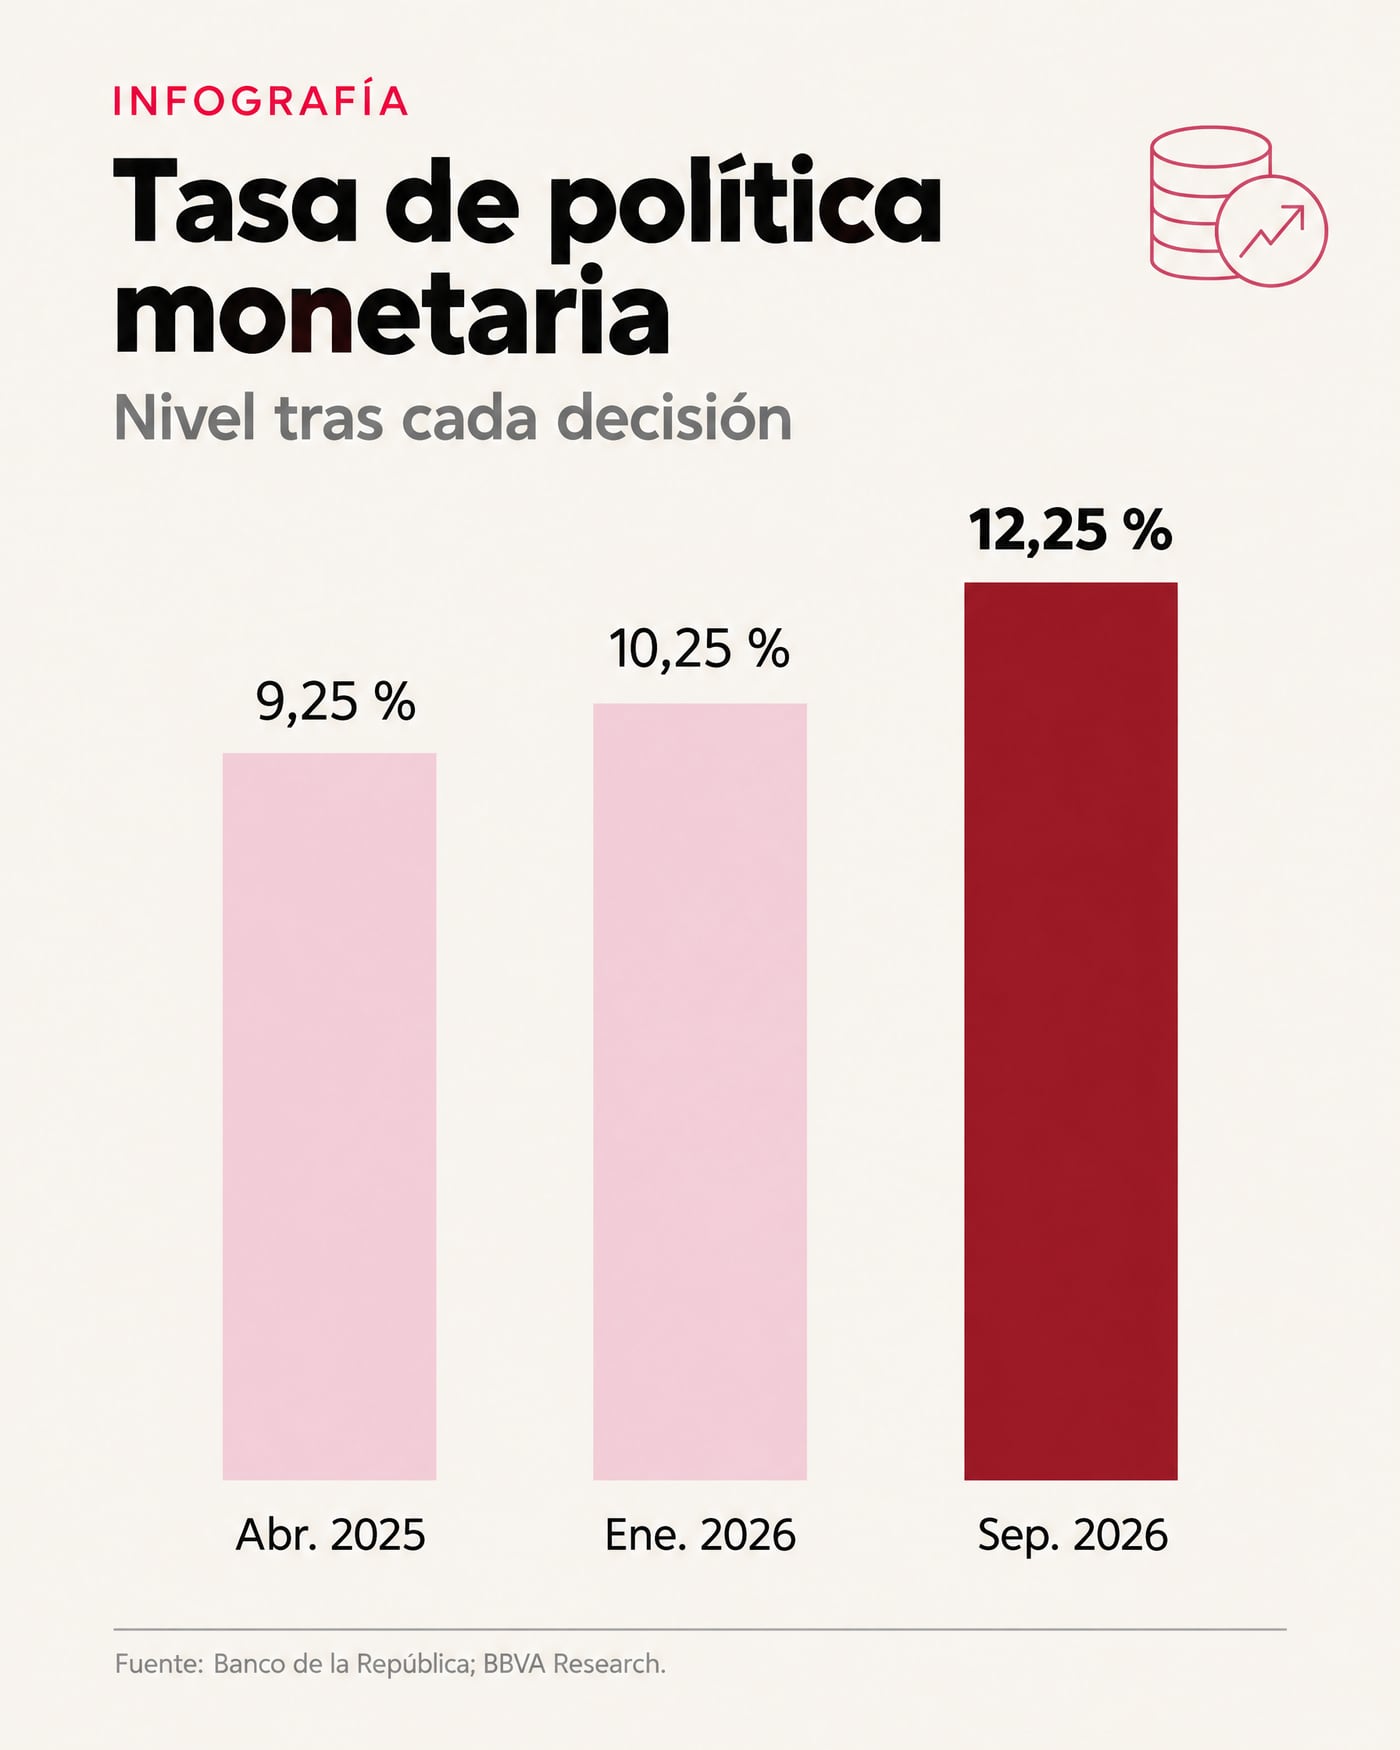
- In January 2026 it raised it 100 basis points, to 10.25%, and in September 2026 it reached 12.25%.
- The reason: inflation rose again, to 6.2% annually in August 2026.
- High rates make credit more expensive and can cool housing prices; investing without debt avoids that cost.
Infographic
Monetary policy rate
Level after each decision
View data in table
| Apr. 2025 | 9,25 % |
| Jan. 2026 | 10,25 % |
| Sep. 2026 | 12,25 % |
Source: Central Bank; BBVA Research
From the cut to the hike
At the April 30, 2025 meeting, the Banco de la República's board cut its monetary policy rate by 25 basis points, down to 9.25%. It kept it at that level for the rest of 2025, although with split votes at the last meeting of the year.
In 2026 the course changed. According to the bank's minutes, the board raised the rate 100 basis points, to 10.25%, in January 2026. And on September 30, 2026, by majority, it increased it another 25 basis points, up to 12.25%, according to the BBVA Research report.
| Date | Decision | Rate |
| April 30, 2025 | 25 bp cut | 9,25 % |
| January 2026 | 100 bp hike | 10,25 % |
| September 30, 2026 | 25 bp hike | 12,25 % |
Sources: Portafolio, Banco de la República minutes, and BBVA Research.
Why rates rose
The central bank uses the interest rate to control inflation. According to BBVA Research, the September 2026 decision responded to annual inflation rising to 6.2% in August and worsening inflation expectations, despite signs of economic slowdown and a weak labor market.
When money is more expensive, consumption and credit tend to moderate, which helps curb prices. The cost is less economic dynamism.
Effects on housing and credit
Higher rates usually make mortgage and consumer loans more expensive. For those buying property with debt, a higher payment reduces the margin between rental income and loan payment. For the market, fewer buyers with credit can put downward pressure on housing demand.
It also changes the comparison between alternatives: when term deposits pay more, the required return on other assets also rises.
Investing without leverage
One difference between fractions and traditional property purchases is that they don't require credit: you buy from 50 USD with your own money. This eliminates the risk of rate changes in the installment, although it doesn't eliminate the inherent risks of the asset, such as occupancy, maintenance, or market value.
Also, CityFraction assets are in various cities and currencies. Colombia's monetary policy affects assets in Colombia, while the Federal Reserve influences Miami, and the European Central Bank impacts Madrid and Capri.
- Compare the estimated return of an asset with low-risk alternatives.
- If you use credit to invest, calculate the installment with rates higher than current ones.
- Diversify across economies with different rate cycles.
What to watch in the coming months
Upcoming decisions will depend on inflation, expectations, and fiscal situation. Analysts consulted by the Colombian press have predicted that rates are unlikely to drop soon. It's advisable to follow the Central Bank's announcements and the monthly CPI from DANE.
All investments carry risks, including capital loss. The returns of CityFraction assets are estimated and not guaranteed.
In short
High rates signal that inflation is not yet under control. For investors, this reinforces the importance of not relying on expensive debt, diversifying across currencies, and analyzing each asset with its own numbers.
Frequently asked questions
What is the Central Bank's rate?
On September 30, 2026, the board raised it to 12.25%, according to BBVA Research.
Why did the Central Bank raise the rate in 2026?
Because inflation rose again, reaching 6.2% annually in August 2026, and expectations worsened.
Do high rates affect fractions?
There is no credit installment because you buy with your own money, but rates influence the economy, demand, and asset values.
Fonts
Public data consulted for this item. Figures may be updated after the consultation date.
- 1.Portfolio: the Central Bank lowered the interest rate to 9.25% (April 30, 2025) · consultado el October 12, 2026
- 2.BBVA Research: BanRep raised the monetary policy rate in September 2026 · consultado el October 12, 2026
- 3.Bloomberg Línea: Colombia’s inflation closed 2025 at 5.1% (DANE) · consultado el October 12, 2026
Explore open properties
Accommodations with fractions from 50 USD.
Conversation
What do you think of this article?
Educational content. Returns and figures are estimates or illustrative examples and do not constitute advice or guarantee. Read the risk information.